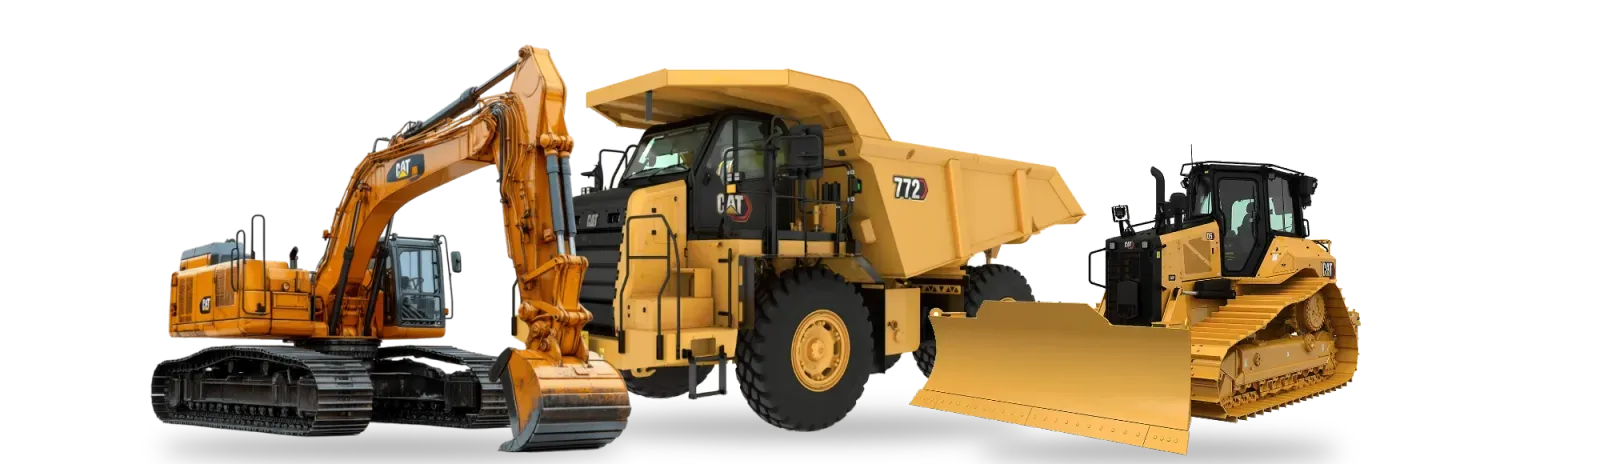
What yellow goods finance covers
Yellow goods is the industry name for earthmoving and construction machinery: excavators, wheel loaders, dozers, graders, skid steers, backhoes, telehandlers, rollers and compactors. The name comes from the colour most of them are painted.
Like other equipment finance, these machines are funded with secured loans or leases through the business. Good machines hold their value, so lenders treat them as solid security, and that keeps the rate sharper than an unsecured business loan.
Who yellow goods finance suits
Earthmoving contractors
Excavators, loaders and dozers for site prep, trenching, bulk earthworks and civil work.
Owner-operators
An experienced operator buying a first machine and going out on their own, often starting with a mini digger or skid steer.
Builders and landscapers
Compact machines that save hiring costs on residential and commercial jobs.
Civil and mining services
Graders, rollers and heavier units, often ex-fleet with known hours.
Hire businesses
Adding machines to a hire fleet, where a facility with a limit saves separate applications.
Farmers
Loaders, skid steers and small excavators for the property. See agricultural finance for tractors and headers.
Machines we fund
Excavators
From mini diggers for residential jobs to 30 tonne units for civil work. See excavator finance for the detail.
Loaders and skid steers
Wheel loaders, track loaders, skid steers and compact track loaders, new and used.
Dozers, graders and more
Dozers, graders, telehandlers, backhoes, rollers and compactors, including ex-fleet units with known hours.
Loaders, skid steers and dozers
Skid steers and compact track loaders
Often the next machine after a mini digger. They're cheap to run, easy to move and fund like any other compact machine. Buckets, forks, augers and sweepers bought with them can usually go in the same loan.
Wheel loaders
Used for loading trucks, stockpiles and quarry work. Good loaders hold their value, and ex-fleet units with known hours come up often, which gives lenders plenty to go on.
Dozers and graders
Bigger ticket machines, usually bought by civil and mining contractors with the work to match. Lenders look closely at contracts, hours and condition, and a balloon is common to keep repayments in line with the work.
Excavators
The most common machine in this category, and they fund well. They have their own page covering mini, midi and full size machines, what to check on a used digger and an example repayment for each size. See excavator finance.
Typical terms
Common ranges, not promises. Every lender sets its own policy.
- Term: often three to seven years. Older machines may be capped by age or hours at the end of the loan.
- Balloon: common, to keep repayments down while you build up work. Handy if you will upgrade in a few years, costly if you plan to run the machine for a decade.
- Deposit: not always needed for established businesses. It helps for new ABNs, older machines and private sales.
- Structure: chattel mortgage is the most common, with finance leases and rentals also available.
- Repayments: some lenders will shape repayments around quieter periods if your work depends on the weather or big projects.
An example repayment
Illustrative only. At an example rate of 9.50% p.a. over five years, fees not included.
| Machine | Repayment | Total repaid |
|---|
| $85,000 compact track loader, no balloon | $1,785 a month | $107,109 |
| $220,000 wheel loader, no balloon | $4,620 a month | $277,225 |
| $220,000 wheel loader, $44,000 balloon | $4,045 a month | $286,680 |
On the wheel loader, the balloon lowers the repayment by about $576 a month and adds about $9,500 in interest, with $44,000 due at the end. If you plan to trade the machine in around then, its resale value can cover the balloon. If you plan to keep it, you will need to pay or refinance that lump sum.
These figures are illustrative only. They are not a quote, a current rate or an offer of credit. Your rate, fees and terms depend on the lender, the machine and your circumstances. Repayments are calculated in arrears and rounded.
What lenders look at
Time in business and on the tools
Around two years of ABN history opens the most doors, but operating experience counts for a lot. A new ABN run by an experienced operator is a very different risk to a new business with no background.
The machine
Brand, age, hours and condition. Mainstream brands with good resale fund easily. Older or less common machines may need a deposit or a shorter term.
Your work
Contracts or a steady pipeline of work give lenders confidence the repayments are covered, particularly on bigger machines.
Your financials
Full doc, or low doc on your ABN, BAS and bank statements if your books are behind.
Buying smart
Auctions
Machinery auctions move fast. Get approved before you bid so you know your limit and can settle quickly.
Private sales
Fine to finance, as long as the lender can confirm ownership and that nothing is owing on the machine. A PPSR search on the serial number shows whether money is still owed against it.
Attachments and transport
Buckets, hammers, forks, tilt hitches and the float to move the machine can often go in the same deal rather than being funded separately. See trailer finance for plant trailers.
What to have ready
- ABN, entity details and GST registration status
- Recent BAS lodgements and business bank statements
- Financials and tax returns if you are going full doc
- A summary of your operating experience and the work lined up
- A quote, tax invoice or auction details for the machine and attachments
- Serial number, hours and service history on a used machine
Yellow goods finance questions
Can I finance used earthmoving gear?
Yes. Used and ex-fleet loaders, dozers and diggers are funded every day. Expect the lender to look at hours and age, and some cap the machine's age at the end of the loan.
Can a new business get yellow goods finance?
Often, yes, particularly with operating experience, a deposit or work already lined up. The options are narrower than for an established business, which is why comparing matters.
Can I finance a machine bought at auction?
Yes. Get approved before auction day, then send the lender the invoice once you've won. Settlement windows can be short, so it pays to be ready.
Can I finance older machinery?
Often, yes, but expect questions about hours and condition. Some lenders cap the machine's age at the end of the term, which can shorten the loan.
Can I include attachments?
Usually. Buckets, hammers and hitches bought with the machine can typically go into the same loan.
Do I need a deposit?
Not always. Established businesses can often fund the full price. A deposit helps for new ABNs, older machines and private sales.
Chattel mortgage or lease?
Either can work. With a chattel mortgage the business owns the machine from the start, while a lease can suit other tax positions. See chattel mortgage, lease or rental, and have your accountant confirm the tax side.
Can I claim the GST?
If the business is registered for GST and uses a chattel mortgage, it can generally claim the GST on the purchase price in its next BAS. Confirm with your accountant.
Can I finance several machines at once?
Yes. A single facility can be simpler than separate loans when you're adding to the fleet.
Buying a digger? See excavator finance. For everything else, see equipment finance, and if you need the truck to go with it, truck loans.